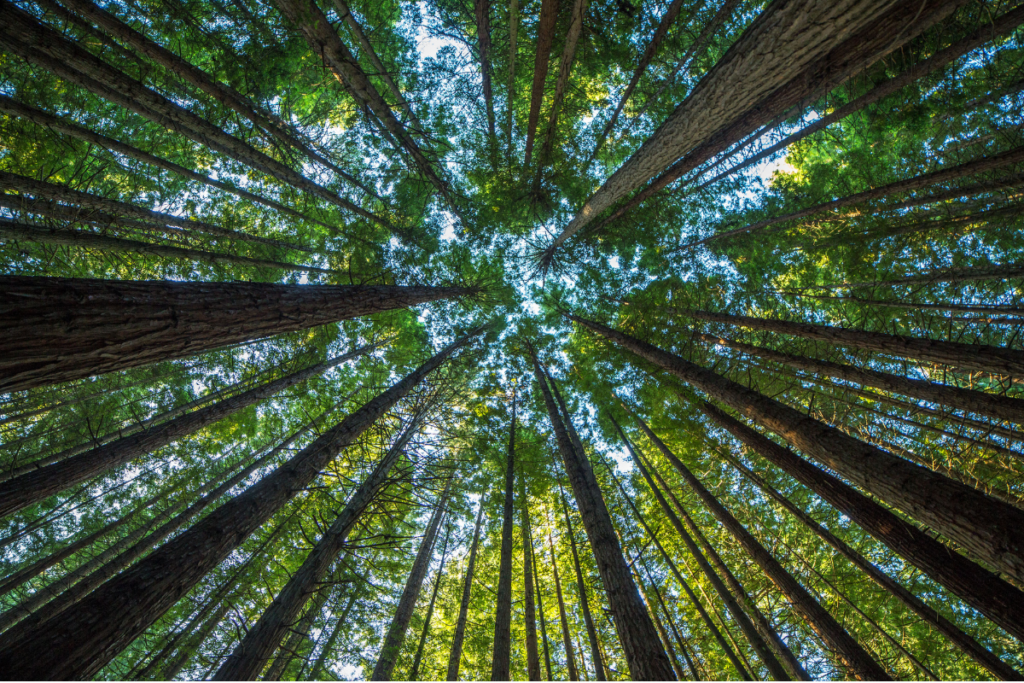
Redwood trees can grow more than 350 feet tall. How do they get there?
They grow up before they grow out.
Early in their development, the tree puts its energy toward height. The branching comes later.
Michael Kitces introduced me to a similar way of thinking about wealth, and the comparison stuck with me. Financial planning teaches diversification for good reason: spread your capital around and reduce the damage any single asset can do.
But look at how entrepreneurs actually create substantial wealth. They often look a lot more like the redwood.
One company. A huge percentage of their net worth in it. Most of their working hours pointed at the same asset. If it works, they frequently stay concentrated for a surprisingly long time before they begin branching out.
Which raises a question I think entrepreneurs need to ask differently: What exactly are you trying to diversify?
Because capital and attention are 2 different resources, and I’ve learned the hard way that diversifying one doesn’t necessarily diversify the other.
There are 2 things on the table
When you buy a business, you’re investing capital and attention simultaneously.
Put $200,000 into an acquisition and you’re obviously allocating capital. But you’re also allocating yourself. You’re hiring people, dealing with customers, watching cash, solving problems, making decisions and figuring out where the next dollar should go.
That’s concentrated capital with concentrated attention.
For an entrepreneur, that combination can be incredibly powerful. You’re taking your capital and putting it behind an asset where your own decisions can affect the value. This is where I depart a little from the traditional concentration-versus-diversification conversation.
I eventually owned companies in distribution, manufacturing, finishing and e-commerce. On paper, I was diversifying: different industries, different customers, different economic drivers. Operationally, I was doing something very different.
I was diversifying my capital while fragmenting my attention.
That’s a dangerous quadrant. You can own 6 businesses in unrelated industries and feel beautifully diversified until 40% of the workforce walks out of one of them, a major customer needs you at another and somebody has a cash problem somewhere else.
Now you’ve got an octopus.
And you can’t manage an octopus.
The 4 ways I think about diversification
Eventually I started thinking about this on 2 axes instead of one. There is capital, which can be concentrated or diversified. Then there is attention, which can be active or passive.
Put those together and you get 4 very different portfolios:

That third box is the one I’d be particularly careful with. If I’m going to concentrate, I want to understand where my edge comes from. Concentrating a large amount of capital in something I can’t influence gives me one of the downsides of concentration without the entrepreneurial advantage I actually care about.
The fourth box became much more interesting to me after I’d spent years buying entire companies. I realized I didn’t have to buy the whole pizza.
I could buy a slice and still have dinner.
The operator doesn’t have to be you
That sounds obvious. It wasn’t obvious to me.
I’d been trained through acquisition entrepreneurship to find a company, put $100,000 or $200,000 of equity into the deal, use leverage, acquire control and then go create value.
Eventually I started asking: what happens if I take that same $100,000 or $200,000 and put it behind somebody who’s better positioned to create the value?
Now I can find an entrepreneur with deep expertise in an industry I don’t know, buy a minority interest and let that person turn the crank.
I’ve done this across:
- a coding academy
- a data-centric marketing company
- film and entertainment
- energy
- other private businesses
I’ve also built exposure to real estate and private credit.
The key distinction is that my capital can go somewhere my attention doesn’t.

That expands the total addressable market for my money without expanding the number of companies I’m personally trying to run. And there are far more ways to access private opportunities today than there were when I started.
The JOBS Act was enacted in 2012, and SEC rules implementing its changes to general solicitation for certain private offerings became effective in 2013. Those changes made it easier for issuers to publicly solicit accredited investors for qualifying private offerings.
You can see the importance of private assets in the portfolios of people who have already created substantial wealth. TIGER 21, whose members are ultra-high-net-worth entrepreneurs and investors, recently reported that private equity and public equity had overtaken real estate among member allocations. Earlier data showed private equity and real estate each representing 28% of member portfolios.
That doesn’t mean copying somebody else’s allocation. It means there are more choices between “buy the whole company” and “buy an index fund” than many acquisition entrepreneurs initially appreciate.
Build a Wealth Stack instead of a Risk Stack
When we acquire a company, we already think in terms of a capital stack. At the bottom, senior secured debt gets paid first and receives a defined return. As I joke, those lenders are basically the mafia: you owe me money this month, and you owe me money next month. That’s what they get.
At the other end sits common equity. You’re paid last, but you own the upside.
Once I started viewing my personal portfolio through the same lens, the pieces clicked together. My capital allocation could serve different purposes:
- Private credit can emphasize income.
- Real estate can combine income, appreciation and tax characteristics.
- Private equity can emphasize long-term appreciation.
- Minority ownership lets me participate in businesses where somebody else has the operating edge.
Meanwhile, I can still own and actively influence the businesses where I have the edge.
I started calling that my Wealth Stack.
The distinction matters because entrepreneurs tend to treat diversification as a question of how many assets they own. I’ve come to think that’s incomplete.
If you own 8 companies and all 8 can ruin your Tuesday, you’ve diversified something. I’m just not sure you’ve diversified the thing you thought you did.
Capital can be spread across assets while attention becomes dangerously concentrated across obligations. And capital can be spread across assets while attention remains concentrated exactly where you’re most valuable.
That’s the version of diversification I wish I’d understood earlier.
Before you add another investment, another company or another asset class, ask what you’re actually trying to diversify: your capital, your attention, or both.